
Accounting for Tech Companies (2026): What to Automate
Tech company accounting in 2026: ASC 606, stock comp, ASU 2025-06 software costs, the new Section 174A deduction, and which finance work to automate first.
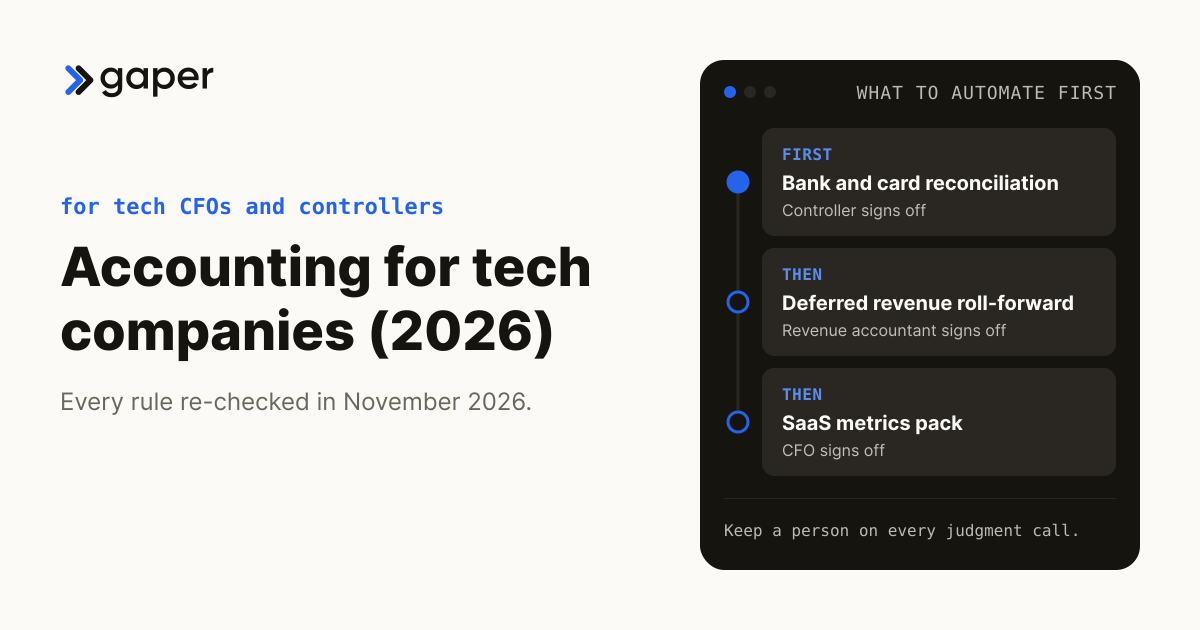
Accounting for tech companies is different because revenue recognition (ASC 606), stock-based compensation (ASC 718), software cost capitalization (ASC 350-40) and multi-currency entities all land on a young finance team at once. Automate the high-volume, rule-bound work first (reconciliation, deferred revenue, SaaS metrics) and keep a person on every judgment call. Every rule below was re-checked in November 2026.
TL;DR: 5 Challenges That Make Tech Company Accounting Different
- Revenue recognition under ASC 606 forces SaaS companies to defer and allocate revenue across performance obligations, not just invoice dates.
- Stock-based compensation (ASC 718) creates phantom expenses that hit your P&L without a single dollar leaving the bank account.
- R&D capitalization vs. expensing decisions under ASC 350-40 directly change your EBITDA, tax liability, and investor narrative.
- Multi-currency and multi-entity structures compound complexity as tech companies scale internationally before they are operationally ready for it.
- Burn rate and runway calculations require real-time data from billing, payroll, and infrastructure costs that traditional accounting software cannot unify.
Table of Contents
- Why Tech Company Accounting Is Different
- 7 Accounting Challenges Unique to Tech Companies
- SaaS Revenue Recognition Flow
- The Tech Company Accounting Stack in 2026
- How AI Is Changing Tech Company Accounting
- Manual vs AI-Powered Month-End Close
- Accounting for Different Tech Stages
- Tech Company Accounting Maturity Model
- How AccountsGPT + Gaper Engineers Serve Tech Companies
- What makes accounting for tech companies different from traditional accounting?
- Why does ASC 606 make SaaS revenue recognition complex?
- When should a SaaS startup implement formal ASC 606 revenue recognition?
- What SaaS metrics do investors expect to see in board reporting?
- How much faster can AI make the month-end close for tech companies?
- Which accounting work should a tech company automate first?
- How does Section 174 affect tech company taxes since 2022?
- Does ASU 2025-06 change how tech companies capitalize software costs?
- What does AccountsGPT from Gaper do differently from traditional accounting software?
Why Tech Company Accounting Is Different
Accounting for tech companies has very little in common with traditional small business bookkeeping. A restaurant recognizes revenue when a customer pays the check. A SaaS company signs a $120,000 annual contract and must recognize that revenue in $10,000 monthly increments across the contract term, allocate it across bundled performance obligations, and handle mid-contract upgrades, downgrades, and churn events that trigger reassessment of the entire arrangement. That complexity is the baseline, not the exception.
The Financial Accounting Standards Board (FASB) issued ASC 606 in May 2014 (ASU 2014-09) jointly with the IASB, to remove inconsistencies and weaknesses in revenue rules and replace industry-specific guidance, the old software rules included, with one model (FASB, ASU 2014-09). Under ASC 606, tech companies must identify the contract, identify each distinct performance obligation, determine the transaction price, allocate that price across obligations, and recognize revenue as each obligation is satisfied. For a SaaS company offering a platform subscription bundled with implementation services, onboarding, and premium support, this creates a waterfall of accounting entries that must be recalculated whenever the contract changes.
Then layer on SaaS-specific metrics that investors and boards demand. Annual Recurring Revenue (ARR), Monthly Recurring Revenue (MRR), Net Dollar Retention (NDR), Customer Acquisition Cost (CAC), and Lifetime Value (LTV) are not standard GAAP measures. They exist in a parallel financial universe that your accounting team must maintain alongside GAAP-compliant financials. Most traditional accountants have never calculated net dollar retention. Most tech CFOs consider it the single most important metric for measuring business health.
Stock-based compensation adds another dimension. Under ASC 718, companies must estimate the fair value of stock options and restricted stock units at the grant date, then expense that value over the vesting period. For a pre-IPO startup issuing options to 200 employees with four-year vesting schedules and various cliff provisions, the accounting burden is significant. And because these expenses are non-cash, they create a divergence between GAAP profitability and actual cash flow that must be clearly communicated to investors.
R&D capitalization creates yet another layer of judgment calls. Under ASC 350-40 (internal-use software) and ASC 985-20 (software to be sold), certain development costs must be capitalized rather than expensed. The decision about when a project moves from the preliminary phase (expense) to the application development phase (capitalize) to the post-implementation phase (expense again) directly impacts your EBITDA, your tax liability, and the story your financials tell investors. Those phases are on their way out under ASU 2025-06, covered in challenge 3. Get it wrong and you face restatement risk. Get it right and you gain a legitimate tool for managing reported earnings.
Finally, multi-entity structures emerge faster at tech companies than almost any other business type. A company might incorporate in Delaware, operate from San Francisco, hire engineers in Eastern Europe, sell to customers in 40 countries, and process payments through a European subsidiary for VAT optimization. Each entity requires its own books, intercompany eliminations, and potentially different local GAAP compliance. The consolidation process alone can consume weeks each quarter without proper automation.
Revenue is also where regulators look hardest: it was the fourth most frequent SEC staff comment topic in the year to June 2025 (EY, September 2025) and was behind 15% of Big R (reissuance) restatements from 2004 to 2023 in Ideagen Audit Analytics data (TheCorporateCounsel.net, 2024), across all registrants.
7 Accounting Challenges Unique to Tech Companies
Every industry has accounting nuances, but technology companies face a concentration of complexity that is unmatched in other sectors. Here are the seven challenges that every tech CFO, controller, and accounting firm serving tech clients must master.
1. Revenue Recognition for SaaS and Subscription Models
SaaS revenue recognition under ASC 606 requires you to break every contract into performance obligations and recognize revenue as those obligations are fulfilled. A straightforward monthly subscription is easy: you deliver the service each month, you recognize revenue each month. But very few SaaS contracts are that simple.
Consider a typical enterprise SaaS deal: $200,000 annual subscription, $50,000 in implementation services, and a commitment to deliver 10 custom API integrations. The subscription revenue is recognized ratably. The implementation services might be recognized over the implementation period (usually 2 to 4 months). The custom integrations might be distinct performance obligations recognized as each is delivered, or they might be combined with the subscription if they are not distinct. That judgment call requires deep understanding of ASC 606's five-step model and the specific guidance for software arrangements.
Mid-contract changes make it worse. When a customer upgrades from 100 seats to 500 seats halfway through the contract, you must determine whether the change is a contract modification treated as a separate contract, a prospective adjustment to the existing contract, or a cumulative catch-up adjustment. It is a separate contract only if it adds distinct goods or services priced at their standalone selling prices (ASC 606-10-25-12). Each treatment produces different revenue numbers for the quarter. Auditors will ask for the documentation supporting your choice.
2. Stock-Based Compensation Accounting
Stock options and RSUs are the currency of tech compensation. Under ASC 718, you must estimate fair value at grant date using a valuation model (typically Black-Scholes for options or Monte Carlo for market-condition awards), then expense that value over the service period. For a company with 300 employees and quarterly grant cycles, you might manage 1,200 or more individual award grants, each with its own grant date, vesting schedule, exercise price, and forfeiture assumptions. The real challenge is the 409A valuation. Private companies need independent appraisals of their common stock value to set option exercise prices. In practice they are refreshed at least every 12 months and after any material event (a funding round, a significant contract win, or a pivot in business strategy), because the regulations presume an independent appraisal reasonable only if it is under 12 months old and reflects later material information (26 CFR 1.409A-1). If your 409A valuation is too low, the IRS can reclassify options as deferred compensation with punitive tax consequences: income inclusion plus an extra 20% tax and interest for the holder (26 U.S.C. 409A). If it is too high, your employees get options that are underwater on day one.
The expense itself creates communication challenges. A startup that is cash-flow positive can report a GAAP net loss because of stock-based compensation expense. CFOs must maintain both GAAP and non-GAAP views of the financials and explain the difference to board members who may not have a finance background. This dual reporting is table stakes for tech companies but rare outside the industry.
3. R&D Cost Capitalization vs. Expensing
When should you capitalize development costs and when should you expense them? For internal-use software under ASC 350-40, costs in the preliminary project stage (conceptual formulation, evaluating alternatives) are expensed. Costs in the application development stage (coding, testing, installation) are capitalized. Costs in the post-implementation stage (training, maintenance) are expensed again.
In practice, drawing these lines is subjective. When does conceptual formulation end and application development begin? If your engineering team uses agile sprints that blend ideation, prototyping, and production coding within the same two-week cycle, mapping those activities to the three accounting phases requires close collaboration between engineering leadership and the accounting team. Many companies default to expensing everything because the capitalization analysis is too complex, but that approach understates their balance sheet assets and overstates their operating losses.
FASB has now answered the agile problem: ASU 2025-06 (September 2025) removes the project stages; see the answer below.
The 2022 tax law change under Section 174 made this even more consequential. From 2022 through 2024, R&D expenditures had to be capitalized and amortized over five years (fifteen years for foreign R&D) for tax purposes, regardless of GAAP treatment. This created a book-tax difference that required deferred tax accounting and left tech companies owing cash taxes even when they reported GAAP losses. The impact was especially painful for startups burning through cash on product development. Section 174A, enacted 4 July 2025, restores a full deduction for US research from 2025; see the Section 174 answer below.

4. Multi-Currency and International Operations
Tech companies go international earlier than almost any other business type. A SaaS product can serve customers in 50 countries from day one, and many startups hire remote engineers across multiple jurisdictions before they reach $1M in ARR. Each international transaction introduces currency risk, and each foreign subsidiary introduces local compliance requirements.
Under ASC 830 (Foreign Currency Matters), you must determine the functional currency for each entity, translate financial statements using appropriate exchange rates (current rate for assets and liabilities, average rate for income statement items), and recognize translation adjustments in other comprehensive income. Transaction gains and losses from settling receivables or payables in a currency other than the entity's functional currency hit your income statement, creating volatility that has nothing to do with your operating performance.
VAT and GST compliance adds further burden. Selling digital services to EU consumers triggers VAT in each customer's country, which a seller with no EU establishment can report through the One-Stop Shop (OSS) non-Union scheme (European Commission). Selling to Australian consumers requires GST registration once those sales reach A$75,000 over 12 months (ATO). Each jurisdiction has different rates, thresholds, and filing frequencies. For a SaaS company with 2,000 customers across 30 countries, the tax compliance matrix is staggering without automation.
5. Deferred Revenue Management
Deferred revenue is the single largest liability on most SaaS balance sheets. When a customer pays $120,000 upfront for an annual subscription, you record $120,000 as deferred revenue (a liability) and release $10,000 to recognized revenue each month. This balance must be tracked at the contract level, not in aggregate, because each contract has its own start date, term, and recognition schedule.
For a company with 5,000 active contracts, the deferred revenue waterfall requires a subledger that most core accounting systems cannot natively manage. Companies either build custom spreadsheets (error-prone and audit nightmares), purchase specialized revenue recognition software (Zuora Revenue, formerly RevPro, Softrax, or similar), or build internal tools. The reconciliation between the deferred revenue subledger and the general ledger is one of the most common audit findings at SaaS companies.
6. Burn Rate and Runway Calculations
Burn rate is not a GAAP concept, but it is arguably the most important number for any venture-backed tech company. Gross burn is total monthly cash outflows. Net burn is total monthly cash outflows minus total monthly cash inflows. Runway is how many months of cash you have left at the current net burn rate. Every board meeting opens with these three numbers.
The challenge is that burn rate requires cash-basis thinking in a world where your books are maintained on an accrual basis. Prepaid annual subscriptions inflate your cash inflows in the month received but should not inflate your perceived runway. Deferred payroll expenses, pending vendor payments, and infrastructure commitments with annual billing cycles all create gaps between what your accrual-based financials show and what your bank account reflects.
Smart CFOs maintain a rolling 13-week cash flow forecast alongside their accrual books. This forecast incorporates known commitments (payroll, rent, vendor contracts), expected collections (based on DSO trends and aging reports), and planned expenditures. Without this dual view, you risk discovering a cash crisis in the same month it happens.
7. Cap Table and Equity Management
A tech company's capitalization table is a living document that changes with every funding round, option grant, exercise, and secondary sale. For accounting purposes, each equity instrument (common stock, preferred stock with liquidation preferences, SAFEs, convertible notes, warrants, and options) must be classified correctly on the balance sheet and measured appropriately.
Convertible instruments are particularly complex. A SAFE (Simple Agreement for Future Equity) might not be debt and might not be equity under GAAP. It could be classified as a liability measured at fair value, with changes flowing through the income statement. Most SAFEs end up as liabilities, though practice differs between ASC 480 and ASC 815-40 (Thomson Reuters, 2023). The accounting treatment depends on the specific terms: valuation caps, discount rates, and conversion triggers. Each funding round can create a new class of preferred stock with distinct rights and preferences that affect the fair value of all existing instruments.
For companies approaching an IPO or acquisition, the cap table becomes even more critical. Waterfall analyses that model how proceeds flow to different share classes under various exit scenarios are essential for understanding what each stakeholder actually receives. These analyses must be maintained in real time and reconciled with the accounting records. Errors in cap table management have derailed acquisitions and delayed IPOs.
SaaS Revenue Recognition Flow
Here are the ASC 606 five steps for the $250,000 bundled deal from challenge 1.
- Identify the contract. The order form, plus any side letter that changes rights.
- Identify the performance obligations. The subscription is one. Implementation and each integration are separate only if distinct; test it.
- Determine the transaction price. $250,000, adjusted for expected overages, credits and discounts.
- Allocate the price. By standalone selling price, not invoice lines.
- Recognize revenue. Subscription ratably over 12 months, a distinct implementation over its 2 to 4 months, integrations on delivery. Anything billed earlier sits in deferred revenue.
Struggling with SaaS Revenue Recognition?
AccountsGPT automates ASC 606 allocations. Gaper engineers build custom integrations with your billing stack. Book a free AI assessment.
The Tech Company Accounting Stack in 2026
No single tool handles every dimension of tech company accounting. The modern finance team builds a stack of specialized tools, connected through APIs and automation layers. Here is the category map, checked at each vendor in November 2026. For prices and a ledger-by-ledger comparison, see our guide to accounting software for SaaS companies.
| Category | Top Options | Best For |
|---|---|---|
| Core Accounting (GL) | QuickBooks Online, Xero, NetSuite | QBO for seed-stage; Xero for international; NetSuite for Series B+ |
| SaaS Metrics | ChartMogul, Baremetrics, ProfitWell Metrics (Paddle) | ARR/MRR tracking, cohort analysis, churn monitoring |
| Subscription Billing | Stripe Billing, Chargebee, Recurly | Automated invoicing, dunning, revenue recognition triggers |
| Revenue Recognition | Zuora Revenue (formerly RevPro), Softrax, Leapfin (Airwallex) | ASC 606 compliance, deferred revenue subledger |
| Cap Table Management | Carta | Equity tracking, 409A valuations, waterfall modeling |
| Expense Management | Brex (Capital One), Ramp, BILL Spend & Expense (formerly Divvy) | Corporate cards, automated categorization, spend controls |
| AI Accounting Layer | AccountsGPT (Gaper.io), Vic.ai, Trullion | Automated reconciliation, anomaly detection, forecasting |
| Tax Automation | Avalara, TaxJar, Stripe Tax | Sales tax and VAT/GST calculation and filing |
| FP&A / Forecasting | Lucanet xP&A (built on Causal), cfo.ai | Rolling forecasts, scenario modeling, board reporting |
What changed since the last version of this table:
- Gone or closing: Pulley closes on 8 December 2026 (Pulley); AngelList's cap table now serves only companies using its roll-up or consolidation vehicles (AngelList); the AITax site no longer resolves, so Stripe Tax replaces it.
- Acquired: Capital One closed on Brex on 7 April 2026 (Capital One); Airwallex announced it was buying Leapfin on 4 June 2026 (Airwallex); HiBob bought Mosaic in 2025 (HiBob) and folded it into Bob Finance, which HiBob says is being redesigned (HiBob), so it is off the list; Causal joined Lucanet in 2024 (Lucanet).
- Renamed: Divvy is BILL Spend & Expense, RevPro is Zuora Revenue, and Runway pivoted into cfo.ai, an AI CFO agent, in September 2026, SiliconANGLE reported (SiliconANGLE).
The critical insight is that these tools must talk to each other. Stripe sends billing data to your GL. Your GL feeds your SaaS metrics platform. Your SaaS metrics feed your FP&A tool. Your cap table platform needs your 409A data. The companies that build clean integrations between these systems close their books in 5 days. The companies that rely on manual exports and spreadsheet reconciliations take 15 days or more and introduce errors at every handoff.
How AI Is Changing Tech Company Accounting
Artificial intelligence is not replacing accountants at tech companies. It is replacing the 60% of accounting work that should never have required a human in the first place. Transaction categorization, bank reconciliation, invoice matching, and anomaly detection are pattern recognition tasks. AI excels at pattern recognition. The result is that a finance team of three people with AI tooling can now produce output that previously required a team of eight.
Revenue recognition automation. AI systems can ingest contract terms, identify performance obligations, calculate standalone selling prices using historical data, and generate the allocation and recognition schedules automatically. What used to require a revenue accountant spending two days per complex contract now takes minutes. The AI flags edge cases (variable consideration, right of return, contract modifications) for human review rather than processing them silently.
Predictive burn rate and runway. Traditional burn rate is backward-looking: you look at last month's cash outflows and project forward. AI-powered forecasting incorporates hiring plans, contract renewals, seasonal patterns, and vendor payment schedules to produce a dynamic burn rate forecast that updates in real time. When your burn rate trends upward because you onboarded three new engineers, the AI recalculates runway instantly and alerts the CFO if it drops below the 12-month threshold.
Automated SaaS metrics. Calculating net dollar retention requires tracking expansion revenue, contraction revenue, and churn for every customer cohort across every billing period. Doing this manually in a spreadsheet at scale is a formula for errors. AI pulls data directly from the billing system, applies the correct calculations, segments by cohort and time period, and produces investor-ready metrics with audit trails showing every data point.
Real-time financial dashboards. The monthly financial close exists because it historically took time to collect, reconcile, and report financial data. AI-powered continuous accounting reduces that lag. When every transaction is categorized, matched, and posted in real time, the distinction between "closed" and "open" periods blurs. CFOs at AI-forward tech companies now have access to real-time P&L, balance sheet, and cash flow views rather than waiting for a monthly snapshot.
Anomaly detection and fraud prevention. AI excels at identifying transactions that break established patterns. An expense report with a round-dollar amount at a vendor you have never used, a duplicate payment to a supplier, or a journal entry posted at 2 AM that reverses itself two days later. These anomalies are buried in thousands of transactions each month. AI surfaces them instantly, letting your team investigate the 15 transactions that matter rather than reviewing all 15,000.
Adoption has leveled off: 59% of finance leaders told Gartner in 2025 that they use AI in the finance function, against 58% a year earlier (Gartner, November 2025).
Whether any of this survives an audit depends on supervision: approval before anything posts, a log of every agent decision, a named person signing the close (human-in-the-loop AI). Gaper is the AI-native implementation partner that deploys supervised AI agents you own. For FP&A, close and reporting, see AI agents for finance teams; to compare agent-building platforms, see Relevance AI alternatives.
Manual vs AI-Powered Month-End Close
The month-end close is where the gap between traditional and AI-powered accounting is most visible. Here is a side-by-side comparison.
| Close task | Manual close | AI-powered close | Who signs off |
|---|---|---|---|
| Bank and card reconciliation | Matched line by line after month end | Matched as transactions post; exceptions only | Controller |
| Deferred revenue roll-forward | Rebuilt from billing exports | Regenerated when a deal or modification is booked | Revenue accountant |
| Accruals and prepaids | Collected by email | Drafted from POs and contracts, source attached | Controller |
| Intercompany and FX | Manual eliminations and rate lookups | Rule-based, differences flagged | Controller and tax |
| SaaS metrics pack | Rebuilt every month | Recomputed continuously with an audit trail | CFO |
| Variance review | Done last, under deadline | Flagged during the month with a drafted explanation | Controller |
For scale, APQC's benchmark of about 2,300 organizations put the median close at 6.4 calendar days, the slowest quarter at 10 or more (CFO.com, 2018). FloQast's 2026 vendor study of US and UK teams reports 6.7 days for the most AI-mature teams against 8.7 for the least (FloQast, August 2026). More on matching: can AI handle bank reconciliation.
Accounting for Different Tech Stages
The accounting needs of a pre-seed startup with 3 employees are fundamentally different from those of a Series C company preparing for IPO. Over-investing in accounting infrastructure too early wastes capital. Under-investing too late creates restatement risk and delays fundraising. Here is the right framework for each stage.
Stage 1: Pre-Seed / Seed Stage
ARR: $0 to $1M | Team: 2-15 people
Accounting stack: QuickBooks Online or Xero. Possibly a fractional bookkeeper (10-15 hours/month). Brex or Ramp for expense management.
Key priorities: Accurate burn rate tracking. Clean separation of business and personal expenses. Proper documentation of SAFE and convertible note agreements. Basic revenue tracking (even if it is just a spreadsheet matching Stripe payouts to invoices).
Common mistakes: Not tracking R&D expenditures for Section 174A and the research credit, which a qualified small business can apply to up to $500,000 of payroll tax (IRS). Mixing entity types (paying personal expenses from the business account). Not maintaining a cap table from day one.
Stage 2: Series A Stage
ARR: $1M to $10M | Team: 15-80 people
Accounting stack: QBO or Xero with a dedicated bookkeeper or outsourced accounting firm. Carta for cap table. A SaaS metrics tool (ChartMogul or Baremetrics). Consider a part-time or fractional CFO.
Key priorities: Implement proper ASC 606 revenue recognition (investors and auditors will ask). Build a deferred revenue schedule. Start tracking SaaS metrics formally (ARR, MRR, NDR, CAC, LTV). Establish a monthly close process that produces financials within 15 business days. Prepare for your first audit (many Series A investors require audited financials within 12 months).
Common mistakes: Recognizing annual prepaid revenue upfront. Not implementing a chart of accounts that separates COGS from operating expenses (critical for gross margin reporting). Ignoring sales tax nexus as the customer base grows across states. Since Wayfair (2018), physical presence is not required (Cornell LII).
Stage 3: Series B-C Stage
ARR: $10M to $100M | Team: 80-500 people
Accounting stack: Migrate to NetSuite or Sage Intacct. Implement revenue recognition software (Zuora Revenue or Softrax). Formal FP&A tooling (Lucanet xP&A, cfo.ai). Full-time CFO and controller. External audit firm (usually a Big 4 or national firm by Series C).
Key priorities: Multi-entity consolidation (especially if you have international subsidiaries). Intercompany transfer pricing documentation. SOC 2 compliance and its impact on financial controls. Stock-based compensation expense becoming material. International tax structuring. Audit readiness year-round, not just at year-end.
Common mistakes: Not hiring a controller early enough (the CFO should not be closing the books). Delaying the ERP migration until the chart of accounts is already a mess in QBO. Not establishing an internal audit function before the external auditors require one.
Stage 4: Growth / Pre-IPO Stage
ARR: $100M+ | Team: 500+ people
Accounting stack: NetSuite or SAP with full ERP implementation. BlackLine or FloQast for close management. Workiva for SEC reporting. Big 4 audit firm. Internal accounting team of 10-25 people.
Key priorities: SOX 404 compliance (internal controls over financial reporting). SEC reporting readiness (10-K, 10-Q filing requirements). PCAOB audit standards. Segment reporting under ASC 280 (expanded by ASU 2023-07). Earnings per share calculations under ASC 260. Tax provision automation for quarterly filings. Investor relations and earnings call preparation. Expense disaggregation (ASU 2024-03), required of public business entities for annual periods beginning after 15 December 2026.
Common mistakes: Discovering material weaknesses during the IPO audit that could have been remediated years earlier. Not having three years of audited financials ready when the IPO window opens. Underestimating the time required for S-1 preparation (typically 6 to 12 months of focused work).
Tech Company Accounting Maturity Model
How accounting capabilities progress from founding through IPO.
| Level | Stage | Close | What to automate |
|---|---|---|---|
| 1. Reactive | Pre-seed / seed | Caught up before a board meeting | Bank feeds, expense categories |
| 2. Structured | Series A | Monthly, within 15 business days | Reconciliation, deferred revenue, SaaS metrics |
| 3. Scaled | Series B-C | Monthly, multi-entity | Consolidation, FX, accrual drafts |
| 4. Public-ready | Pre-IPO | On an SEC timetable | Continuous close, every action logged |
At Any Stage, Gaper Has Your Finance Stack Covered
AccountsGPT for automated reconciliation. Gaper engineers for custom Stripe, NetSuite, and Carta integrations.
14 verified Clutch reviews | Harvard & Stanford Alumni
How AccountsGPT + Gaper Engineers Serve Tech Companies
AccountsGPT: AI-Powered Accounting Agent
Automated Bank Reconciliation. Auto-matches 94% of transactions using ML pattern recognition. Learns your vendor naming patterns, recurring charges, and intercompany transfers. Flags the 6% that need human review with suggested categories.
SaaS Metrics Engine. Pulls billing data directly from Stripe, Chargebee, or Recurly. Calculates ARR, MRR, NDR, CAC, LTV, and 20+ SaaS metrics automatically. Segments by cohort, plan tier, geography, and acquisition channel.
Financial Forecasting. Builds rolling 13-week cash forecasts, 12-month P&L projections, and scenario models. Updates in real time as new transactions post. Provides burn rate alerts when runway drops below configurable thresholds.
Revenue Recognition Automation. Ingests contract terms, identifies performance obligations, calculates standalone selling prices from historical data, and generates ASC 606-compliant recognition schedules. Handles modifications and variable consideration.
AccountsGPT also does tax preparation and payroll.
Gaper Engineers: Custom Finance Integrations
Stripe to NetSuite Sync. Custom middleware that maps Stripe events (subscriptions, invoices, refunds, disputes) to NetSuite journal entries in real time. Handles multi-currency, deferred revenue, and intercompany allocations.
Carta Integration. Syncs cap table data with your GL for automated stock-based compensation expense calculations. Pulls 409A valuations, vesting schedules, and exercise activity into accounting entries.
Custom Financial Dashboards. Real-time dashboards combining GAAP financials with SaaS metrics, burn rate, and operational KPIs. Built on your existing data warehouse (Snowflake, BigQuery, Redshift) with drill-down to transaction-level detail.
Multi-Entity Consolidation Tools. Automated intercompany elimination, currency translation, and consolidated reporting for companies with 3 to 30 entities. Replaces the spreadsheet-based consolidation process that breaks every month.
For reconciliation, AP and AR exceptions and close prep with approvals and a full audit trail, see AI agents for accounting.
Ready to Modernize Your Tech Company's Finance Stack?
Tell us about your accounting challenges. We will recommend the right combination of AI automation and custom engineering.
14 verified Clutch reviews | Harvard & Stanford Alumni | No commitment required
What makes accounting for tech companies different from traditional accounting?
Tech companies deal with subscription-based revenue recognition (ASC 606), stock-based compensation (ASC 718), R&D capitalization decisions, deferred revenue as a primary balance sheet liability, and rapid international expansion.
These complexities compound because they happen simultaneously in fast-growing companies. A traditional retail or services business typically faces one or two of these issues. A Series B SaaS company faces all of them at once.
Why does ASC 606 make SaaS revenue recognition complex?
ASC 606 requires companies to break each contract into distinct performance obligations and recognize revenue as each is satisfied rather than at invoice date. A $120,000 annual contract must be recognized in $10,000 monthly increments, and mid-contract upgrades or downgrades trigger reassessment of the whole arrangement.
When should a SaaS startup implement formal ASC 606 revenue recognition?
At Series A or when ARR exceeds $1M, whichever comes first. Before that, a spreadsheet-based deferred revenue schedule is usually adequate, but multi-year contracts, bundled services, or usage-based pricing require a formal methodology and ideally a revenue recognition tool.
Waiting until an audit finding forces the change means retroactive adjustments that consume weeks of controller time.
What SaaS metrics do investors expect to see in board reporting?
At a minimum, investors expect to see ARR (or MRR), net dollar retention (NDR), gross margin, customer acquisition cost (CAC), LTV-to-CAC ratio, and burn rate with implied runway.
As the company scales, cohort-level analysis of expansion and contraction revenue, logo churn versus dollar churn, and CAC payback period by channel become standard expectations. These metrics are not optional for fundraising conversations at Series A and beyond.
How much faster can AI make the month-end close for tech companies?
AI automates 90-95% of bank reconciliation, revenue recognition schedules, anomaly detection, and intercompany eliminations, typically reducing the close from 10-15 business days to 3-5 days while improving accuracy.
AI reduces close time primarily through automated bank reconciliation (matching 90-95% of transactions without human intervention), automated revenue recognition schedule generation, real-time anomaly detection that catches issues as they happen rather than during the close review, and automated intercompany eliminations. Companies that implement AI accounting tools typically reduce their close from 10-15 business days to 3-5 business days while improving accuracy. The human team shifts from data processing to exception review and strategic analysis.
Which accounting work should a tech company automate first?
Bank and card reconciliation, then the deferred revenue roll-forward and the SaaS metrics pack. All three are high volume, follow written rules and can be checked line by line. Leave the judgment calls with a person.
How does Section 174 affect tech company taxes since 2022?
From 2022 to 2024 it forced R&D costs to be amortized, raising cash taxes. New Section 174A, enacted 4 July 2025, restores a full deduction for domestic research and software development in tax years beginning after 31 December 2024. Foreign research still amortizes over 15 years.
Under the old rule, amortization began at the midpoint of the year, so a company spending $5M on US R&D in 2022 could deduct only $500,000 that year, then $1M a year (Rev. Proc. 2025-28). The result was a significant increase in taxable income and cash tax liability, even for companies that were unprofitable on a GAAP basis. Under Section 174A (Public Law 119-21), the same spend in 2025 or later is deductible in full, or you can elect to amortize it over at least 60 months (26 U.S.C. 174A).
- Unamortized 2022 to 2024 domestic costs can be deducted in the first tax year beginning after 31 December 2024, or over that year and the next.
- Small businesses ($31 million or less in average gross receipts) could apply 174A back to 2022; that deadline, 6 July 2026, has passed.
- The research credit reduces the 174A deduction unless you elect a reduced credit under Section 280C(c).
Proper planning now means maximizing the R&D tax credit under Section 41 and keeping domestic and foreign research in separate records. This is information, not tax advice.
Does ASU 2025-06 change how tech companies capitalize software costs?
Yes, for internal-use software. ASU 2025-06 removes the preliminary, development and post-implementation stages from ASC 350-40. Capitalization starts once funding is committed and completion is probable. It is mandatory for annual periods beginning after 15 December 2027.
Completion is not probable while novel features are unresolved or requirements are still being substantially revised. Early adoption is permitted, with prospective, modified or retrospective transition. Software you sell stays under ASC 985-20, unchanged (FASB, ASU 2025-06).
What does AccountsGPT from Gaper do differently from traditional accounting software?
AccountsGPT is an AI accounting agent, not traditional software. It actively processes your financial data, learns your transaction patterns, auto-categorizes and reconciles bank feeds, generates revenue recognition schedules from contract terms, produces SaaS metrics from billing data, and forecasts cash flow using predictive models.
Unlike static software that requires manual inputs and rule configuration, AccountsGPT adapts to your specific patterns over time. And because it is part of Gaper's platform, you can pair it with engineers who build custom integrations between your billing, GL, and reporting systems.
Thirty minutes, no commitment. We map one workflow, make the build or buy call, and scope the smallest thing worth shipping.
Frequently asked questions
What makes accounting for tech companies different from traditional accounting?
Why does ASC 606 make SaaS revenue recognition complex?
When should a SaaS startup implement formal ASC 606 revenue recognition?
What SaaS metrics do investors expect to see in board reporting?
How much faster can AI make the month-end close for tech companies?
Which accounting work should a tech company automate first?
How does Section 174 affect tech company taxes since 2022?
Does ASU 2025-06 change how tech companies capitalize software costs?
What does AccountsGPT from Gaper do differently from traditional accounting software?
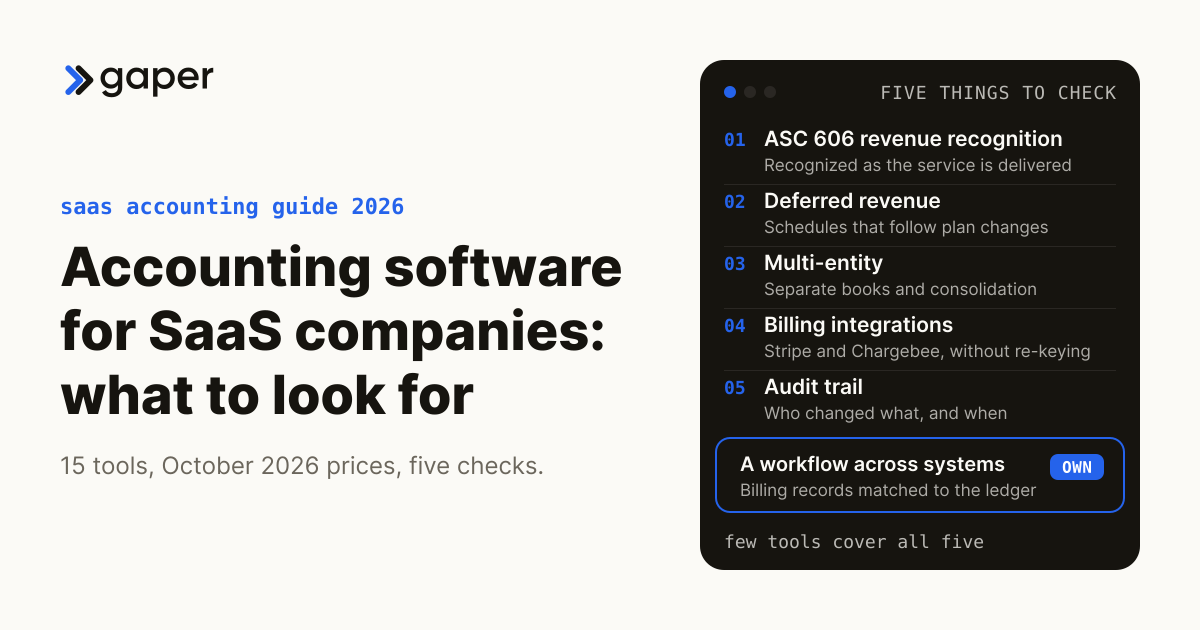
15 Best Accounting Software for SaaS Companies (2026): What to Look For
AI for Tax Season: What Accounting Firms Can Automate Before the Next Deadline
IndustryAutomate Tax Workpaper Preparation: What Automates, What Assists, and What Stays With the Preparer
A step by step look at tax workpaper preparation for CPA firms: which steps automate today, which only draft, and which stay with the licensed preparer.
Sep 21, 2026Ready to turn AI into execution?
Book a free assessment of one workflow. We map it, make an honest build versus buy call before any code, and if an off the shelf product covers the job we will tell you so.