AI in Accounting: 2026 Industry Trends
The 2026 accounting industry trends with current numbers: AI adoption, the CPA pipeline and 150-hour changes, offshoring, CAS growth, pricing and 7216 rules.
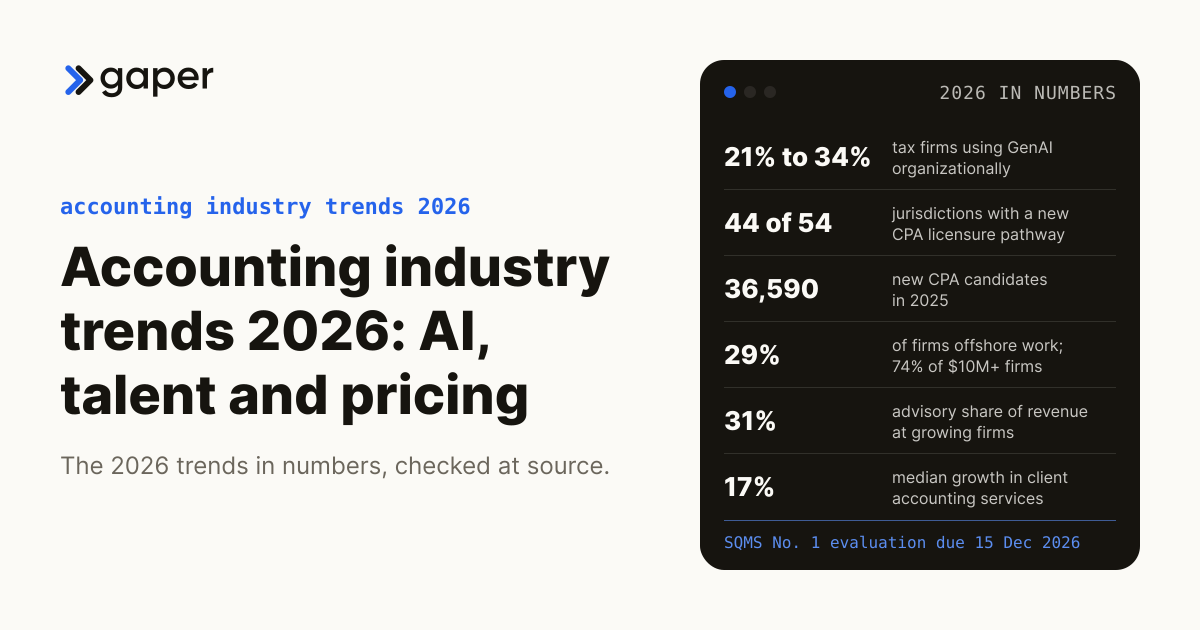
The accounting industry trends that matter in 2026 are AI moving from pilots into firm workflows, a talent pipeline reshaped by new CPA licensure routes and offshoring, advisory and client accounting services outgrowing compliance, and fixed fees replacing the billable hour. Add tighter rules on client data in AI tools; ESG assurance and blockchain audit matter mostly to firms with very large clients.
Updated October 2026: every figure below was checked at its source between 20 and 27 October 2026.
TL;DR: 5 Key Accounting Industry Trends for 2026
- AI is in use at about a third of tax firms. Organizational generative AI use reached 34%, up from 21% a year earlier (Thomson Reuters Institute, 2026).
- The talent squeeze is a headcount decline, and the pipeline is turning. New CPA candidates rose to 36,590 in 2025 (NASBA), and 29% of firms offshore work (2025 MAP Survey).
- Advisory is growing faster than compliance, but it is not yet the majority: 31% of revenue at growing firms (Thomson Reuters).
- Pricing is leaving the hour. Only 10% of CAS practices still bill mainly by the hour (AICPA PCPS and CPA.com, December 2024).
- Client data rules got sharper. The IRS issued AI guidance for tax practitioners in June 2026, and Section 7216 consent and the FTC Safeguards Rule decide how fast AI can touch a client file.
Table of Contents
- The State of Accounting in 2026
- 1 0 Accounting Industry Trends Shaping 2026
- The 10 Trends at a Glance
- How AI Is Transforming Accounting Workflows
- How to Size the ROI for Your Firm
- What This Means for Your Firm
- How AccountsGPT Fits Into These Trends
- The Future Accounting Firm Tech Stack
- Buyer questions: the biggest trends and AccountsGPT
The State of Accounting in 2026
The market grows slowly; how the work gets done is changing fast. IBISWorld puts global accounting services at $653.9 billion in 2026, up about 2.2%, and the US market at $158.4 billion.
AI is spreading from a low base. The Thomson Reuters Institute's 2026 report, surveyed in October and November 2025, found 34% of tax firms using generative AI at the organizational level and 14% using agentic AI. Use outruns policy: Karbon's State of AI in Accounting 2026, with nearly 600 respondents, found 98% of firms using AI but only 21% with an AI policy or strategy.
The talent picture is a decline in people, not a stack of funded vacancies. Bloomberg's March 2024 analysis of BLS data counted about 340,000 fewer accountants and auditors than five years earlier. The BLS counts 1,595,200 employed in 2025 and projects about 115,300 openings a year to 2035. And accounting undergraduate enrollment rose 7.3% in fall 2025, a third straight increase (AICPA, January 2026).
Economics are healthy, which makes change optional now and expensive later. The AICPA PCPS and CPA.com 2025 MAP Survey of 1,073 firms found median net client fee growth of 6.7%, down from 9.1%. Private equity keeps buying, more slowly: 37 deals for US and Canadian firms in Q3 2026, against 42 a year earlier (CPA Trendlines).
| Figure | What it measures | Source |
|---|---|---|
| 21% to 34% | Tax firms using generative AI organizationally, 2025 to 2026 reports | Thomson Reuters Institute |
| 1,595,200 | US accountants and auditors employed, 2025 | BLS |
| 44 of 54 | Jurisdictions with a new CPA licensure pathway, August 2026 | Minnesota Society of CPAs |
| 29% | Firms that offshore work; 74% at $10M+ in net client fees | AICPA PCPS and CPA.com, 2025 |
What actually changed in CPA licensure, and does the new bachelor's-plus-two-years pathway change my 2027 hiring plan?
The 150-hour rule is no longer the only route. Since May 2025 the model law allows a bachelor's degree plus two years of experience and the CPA Exam, and 44 of 54 jurisdictions had enacted a new pathway by August 2026. If your recruiting states have switched, your 2027 entry pool widens.
The AICPA and NASBA boards approved the model legislation on 14 May 2025, when 14 states had already acted. The Minnesota Society of CPAs tracker, updated 12 August 2026, counts 39 jurisdictions that also adopted individual-based mobility; Florida, Maine, Massachusetts, Michigan, North Dakota and Wyoming had not enacted a pathway. Mobility now turns on the CPA's own education, exam and experience, and CPAs licensed as of 31 December 2024 keep their practice rights.
The exam funnel is refilling: NASBA counted 36,590 new CPA candidates in 2025, up from 27,994 in 2024. Effective dates run from 2026 into 2027, so check NASBA's map for each state you recruit in. Where it is live, experience doubles, shifting cost from tuition to your supervision.
10 Accounting Industry Trends Shaping 2026
Ten forces, ordered by urgency. The first three change revenue and staffing this year; trends 6, 7 and 10 matter mainly to larger firms or clients.
1. AI-Powered Automation Is No Longer Optional
The window for treating AI as an experiment is closing. Organizational generative AI use at tax firms rose from 21% to 34% between the Thomson Reuters Institute's 2025 and 2026 reports, and CPA.com and Blue J found 60% of tax professionals using AI for research at least weekly, up from 33% a year earlier (June 2026, over 1,000 respondents).
Current agents draft reconciliations, cash flow forecasts, anomaly flags and consolidations for a person to approve. Tools like AccountsGPT represent this new category: purpose-built AI agents that understand accounting logic, not generic chatbots repurposed for finance. Treat vendor percentages without a published method as hypotheses. Our guide to AI for accounting firms covers where to start.
2. The Accountant Talent Shortage Is Getting Worse
The shortage is real today and easing later, and firms are filling the gap offshore. It bites hardest in tax planning and senior review, and pay follows: the 2025 MAP Survey put median pay for managers with six to seven years' experience at $99,000, up from $86,374.
The 2025 National MAP Survey found 29% of firms offshore, rising to 74% at $10 million or more in net client fees. Among firms that outsource, 51% send individual tax, 42% business tax and 38% client accounting work; 72% use a third-party vendor, 65% send work to India and 33% to the Philippines. For 1040 clients, sending return data abroad brings Section 7216 consent into play, which we weigh in offshore accounting vs AI.
3. Advisory Services Are Replacing Compliance Work
Advisory is growing faster than compliance, but the inversion has not happened yet. Thomson Reuters (December 2025) puts advisory at an average 31% of revenue among firms with revenue growth, 88% of whom say it is outpacing compliance; that average covers growing firms only, not every firm.
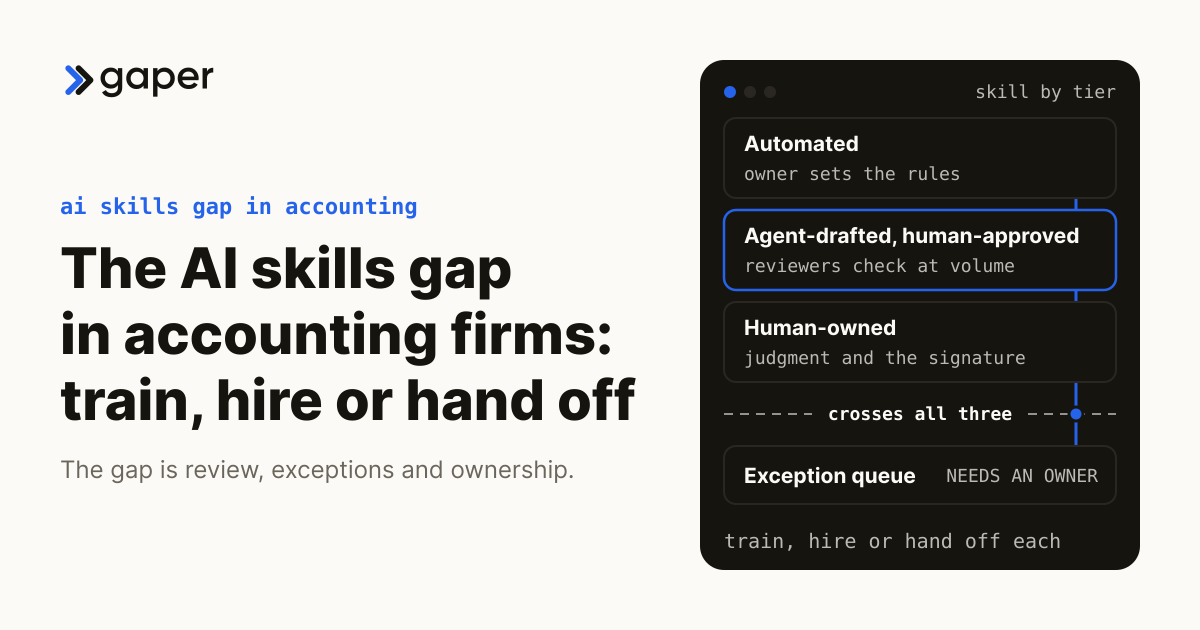
Client accounting services carry the shift. The AICPA PCPS and CPA.com survey of 206 CAS practices found median CAS growth of 17%, and only 10% still billing mainly by the hour (December 2024; the 2026 edition has not reported). The barriers: 52% cite staff skills gaps and 47% client resistance to paying for advice (Thomson Reuters). Freed capacity becomes advisory revenue only if someone can deliver it; see the AI skills gap in accounting firms.
4. Real-Time Financial Reporting Is the New Standard
Clients expect continuous visibility, not a pack two weeks after period end, and the limit is process, not software. Platforms already reconcile bank and ERP data to the ledger daily; firms that get there redesign the workflow rather than automating a batch process.
5. SaaS Consolidation Is Accelerating
A typical firm runs separate ledger, tax, practice management, portal, payroll and time tools, each with its own fee and integration upkeep. Price total ownership, including hours fixing integrations, before renewal season; the direction is fewer systems, with AI moving data between them.
Free for Accounting Firms
Get a Personalized AI Readiness Assessment
We map your close, reconciliation and reporting workflows, then show which ones an AI agent running in your own cloud could take over, and what it would cost to build and run. No commitment required.
6. Blockchain and Distributed Ledger for Audit
Distributed ledgers have practical audit uses, such as continuous testing instead of sampling, but they remain a research programme at large firms. No standard, peer review expectation or client demand pushes a smaller firm toward them in 2026.
7. ESG and Sustainability Reporting Requirements
ESG reporting is regulated in places, but thresholds sit far above a typical client base. California's SB 253 covers entities above $1 billion in revenue; CARB's regulation took effect on 12 October 2026 on approval by the state's Office of Administrative Law (Sullivan & Cromwell, October 2026), with first scope 1 and 2 reports due 10 November 2026. SB 261 is unenforced under a Ninth Circuit injunction. The SEC proposed rescinding its climate rules on 29 May 2026; they never took effect. CSRD now covers EU groups above 1,000 employees and €450 million turnover, from financial years starting 1 January 2027.
8. Cybersecurity as a Core Accounting Competency
Firms hold tax returns, bank details and payroll records, and regulators treat them like financial institutions. On 18 August 2026 the IRS and Security Summit reminded tax professionals they need a written information security plan (IR-2026-92). AI-generated phishing and deepfakes raise the bar on training and multi-factor authentication, and on where your AI runs: an agent inside your own cloud, under your access controls and audit logs, is a different risk from a vendor's multi-tenant service.
9. Remote and Hybrid Workforce Permanence
The remote debate did not end as predicted. Robert Half's Q2 2026 data shows finance and accounting postings 85% fully on-site, 12% hybrid and 3% remote, with 36% of employers raising required on-site days. Among professionals job hunting, 39% name more remote flexibility as a primary motivation, so a firm that offers it now stands out.
10. Client-Facing AI Portals
Some firms let clients ask plain-language questions of their own financials without booking a call, which cuts routine inquiries and helps retention. Firms using AccountsGPT as their back-end intelligence layer can deploy client portals that leverage the same reconciliation and analytics engine, creating a seamless experience.
Which of these trends carry a hard deadline, and which can I defer?
Two carry a date: SQMS No. 1 quality management, effective 15 December 2025 with the first evaluation due by 15 December 2026, and the FTC Safeguards Rule, already in force for tax preparers. California climate reporting binds only $1 billion companies. The rest is positioning with no clock.
Items with a date. Firms doing SAS, SSAE or SSARS work needed a quality management system by the SQMS No. 1 effective date. The FTC names tax preparation firms as financial institutions under the Safeguards Rule, which requires a qualified individual, a written risk assessment, encryption, multi-factor authentication, vendor oversight and FTC notice within 30 days of an event affecting 500 or more consumers. Firms under 5,000 consumers escape only a few provisions.
Items where the clock moved. SB 253 reports are due 10 November 2026; SB 261 is on hold.
Items with no clock. SEC climate rules, the 2027 CSRD scope, blockchain audit and client portals.

The 10 Trends at a Glance
| # | Trend | What changes in 2026 |
|---|---|---|
| 1 | AI-Powered Automation Is No Longer Optional | Tax firm GenAI use: 21% to 34% |
| 2 | The Accountant Talent Shortage Is Getting Worse | New licensure routes; 29% offshore |
| 3 | Advisory Services Are Replacing Compliance Work | Advisory 31% at growing firms; CAS up 17% |
| 4 | Real-Time Financial Reporting Is the New Standard | Continuous visibility over the monthly close |
| 5 | SaaS Consolidation Is Accelerating | Fewer, integrated systems |
| 6 | Blockchain and Distributed Ledger for Audit | No standard or deadline |
| 7 | ESG and Sustainability Reporting Requirements | Binding only on very large companies |
| 8 | Cybersecurity as a Core Accounting Competency | WISP and Safeguards Rule duties |
| 9 | Remote and Hybrid Workforce Permanence | 85% of postings fully on-site |
| 10 | Client-Facing AI Portals | Clients query their own data |
Which of these apply to a firm under 50 people, and which are Big Four problems?
Four apply to almost every small firm: quality management, the Safeguards Rule, licensure and hiring, and pricing. ESG assurance and blockchain audit can wait unless you serve billion-dollar or EU-scoped clients. In the 2025 MAP Survey, 81% of responding firms had revenue of $5 million or less.
That AICPA figure makes a 30-person firm the median reader of this page. Safe to ignore, for now: ESG assurance and distributed ledger audit. Not safe to ignore: SQMS No. 1, which covers sole practitioners doing SAS, SSAE or SSARS work; the Safeguards Rule, which has no small-firm exemption from the rule itself; licensure; and pricing, because automation hits revenue before cost.
How AI Is Transforming Accounting Workflows
Firms start with five workflows, and each holds only if a few conditions are true. We are deliberately not publishing time-savings percentages. We have not run a study we could show you, and the vendor numbers circulating in this category do not come with a method. Use this as a scoping checklist.
| Workflow | What the agent does | What has to be true to trust it |
|---|---|---|
| Bank Reconciliation | Matches feed transactions to GL entries, proposes coding, escalates what it cannot match | Clean feeds, a stable chart of accounts, human sign-off above your materiality threshold |
| Invoice Processing | Extracts line items, applies approval rules, flags duplicates | Documented approval authority and a reviewed rejection path |
| Financial Reporting | Assembles the pack and drafts variance commentary | Agreed report definitions and version control |
| Tax Prep | Pulls source documents, populates schedules, surfaces open questions | Preparer review on every return, with a logged reason for each override |
| Audit Preparation | Gathers support, ties out schedules, builds the PBC list | Evidence stays in your systems, with an audit trail of what the agent touched |
Recovered hours nobody bills are a cost cut at best. Before scaling a pilot, sample its output against a manual baseline and count the exceptions it caught and created.
How is AI changing the accounting profession? AI is taking over the mechanical parts of reconciliation, invoice processing and reporting assembly, with a person still signing off. That frees accountants for advisory work, analysis and client relationships. Agents like AccountsGPT handle multi-client management, anomaly detection and cash flow forecasting.
What are my confidentiality and consent obligations when client data goes into an AI tool?
Three independent duties apply: Section 7216 limits disclosing or using tax return information, the AICPA Code requires a confidentiality agreement or client consent before a vendor sees client data, and the FTC Safeguards Rule requires you to oversee the vendor. Satisfying one does not satisfy the others.
This is information, not legal advice. Staff are not waiting: Thomson Reuters' 2026 Future of Professionals survey of 538 tax and audit professionals found 35% using AI tools their firm has not authorized.
Section 7216. Knowingly or recklessly disclosing or using return information other than to prepare the return carries a fine of up to $1,000, up to a year in prison, or both. Under 26 CFR 301.7216-3(a), other disclosures need the taxpayer's prior written consent, and for 1040-series clients Revenue Procedure 2013-14 sets its format and wording (a generic "software vendors" line will not do). The preparer-to-preparer exception in 301.7216-2(d)(1) covers preparation and auxiliary services, not substantive determinations, and only for preparers in the United States. Section 301.7216-3(b)(4) bars consent to send a 1040 client's Social Security number to a preparer abroad, with a narrow safeguard exception in (b)(4)(ii). Owning the AI system does not remove this: ownership changes control over region, logs and masking, not the consent duty. See Section 7216 consent for AI tools.
The AICPA Code, the Safeguards Rule and the IRS. Interpretation 1.700.040 requires a confidentiality agreement with the provider or specific client consent. Safeguards Rule section 314.4(f) requires you to choose capable providers, bind them by contract and reassess them. The IRS Office of Professional Responsibility's Issue Number 2026-19 (24 June 2026) confirms Circular 230 duties of diligence and competence apply to AI use, and warns against uploading sensitive client data to unsecured or public systems.
Get each vendor's terms on training, data location, subprocessors and retention in a signed agreement. Then amend the engagement letter: John Raspante of McGowan recommends disclosing AI use there, with a client opt-out (Accounting Today, April 2026).
How to Size the ROI for Your Firm
We are not going to hand you a model with our numbers pre-filled in the input cells, because the inputs that decide the answer are yours.
| Input | Where to get it |
|---|---|
| Hours per week on the target workflow | Time entries from the last two busy-season months |
| Share of hours a person must still review | Decide before the pilot, then hold to it |
| Blended charge-out rate | Your realization data; the 2025 MAP Survey's median manager billing rate was $198 an hour |
| Billable demand to absorb freed hours | Pipeline, not aspiration; if zero, the saving is a cost cut |
| Implementation and run cost | Vendor or build fee plus your team's supervision hours |
The one published benchmark is Thomson Reuters' 2025 Future of Professionals estimate of a $32 billion combined annual impact across US legal and tax and accounting from time AI frees up. It becomes revenue only where demand exists, so your own time entries remain the baseline.
Who is liable when the AI is wrong, and how does this land in peer review?
You are. Professional responsibility does not transfer to a vendor, standard setters apply existing standards rather than AI-specific ones, and reviewers will look for documentation showing a person evaluated the output. Build that file now while it is cheap.
The PCAOB's amendments to AS 1105 and AS 2301, effective for fiscal years beginning on or after 15 December 2025, address technology-assisted analysis generally, not AI specifically (CalCPA, August 2026). Under AU-C 230, working papers must let an experienced auditor new to the engagement follow the procedures and judgments; "an AI tool was used" does not, and reviewers will probe automation bias.
Any tool used in attest work belongs in your SQMS No. 1 risk assessment. COSO's Achieving Effective Internal Control Over Generative AI (February 2026) maps AI uses to controls with testing templates. And Stan Sterna of Aon, which administers the AICPA Member Insurance Program, reports no substantive AI claim activity yet, while insurers already ask whether firms police AI use and have protocols.
What This Means for Your Firm
Calibrate the response to firm size and technology maturity.
| # | Firm size | Priority | Action |
|---|---|---|---|
| 1 | Solo Practitioners | Start with AI tax preparation and bookkeeping tools for the work that fills your evenings. | Baseline one workflow, then measure it again 90 days after go-live. |
| 2 | Small Firms (5-20 employees) | Implement AccountsGPT for multi-client management. The talent squeeze hits hardest here, because you cannot outbid larger firms. | Deploy on reconciliation, invoicing and client reporting, one at a time. Begin SaaS consolidation. |
| 3 | Mid-Size Firms (20-100 employees) | Full AI workflow transformation, with one plan for automation, advisory, portals and security. | Commission custom integrations built to run in your own cloud, so the firm owns the system afterwards. Deploy AccountsGPT as the core AI layer. Build client-facing portals. Establish ESG reporting capability. |
| 4 | Large Firms (100+ employees) | Enterprise AI strategy plus custom development for proprietary workflows. | Scope a custom build that runs inside your cloud and stays your property, including the prompts, the evaluation set and the deployment pipeline. |
If automation removes the hours, how do I price the work without cutting my own revenue?
Reprice the affected service line to a fixed or value fee before you deploy the automation, not after. Under hourly billing, a reconciliation that drops from four hours to fifteen minutes destroys revenue unless demand absorbs the time, and with a stable client book it usually does not.
The profession is moving: the 2025 MAP Survey reports a steady shift toward value and fixed pricing, and Ignition's July 2025 survey of 219 US firms found 80% planning fee rises for 2026, 37% by 5% and 30% by 10%.
Three problems follow. Realization and utilization stop meaning much, so agree replacement metrics such as margin per client before the switch. Bonuses tied to chargeable hours penalize the people you need to adopt the tool, so fix them the same quarter. And repricing a whole book risks churn, so start with one predictable line, usually bookkeeping. Our analysis of automation fee erosion runs the numbers.
How AccountsGPT Fits Into These Trends
AccountsGPT is not a generic AI chatbot adapted for accounting. It is a purpose-built AI agent designed by Gaper.io specifically for the accounting profession. It understands double-entry bookkeeping, GAAP and IFRS standards, multi-entity consolidation, and the nuances of client management that general-purpose AI tools miss entirely. It also does tax preparation and payroll.
Here is what AccountsGPT handles in production today:
| Capability | What it does |
|---|---|
| Automated Bank Reconciliation | Matches transactions across multiple bank feeds and GL entries. Flags anomalies for human review and leaves the sign-off with your staff. |
| Cash Flow Forecasting | Analyzes historical patterns, seasonal trends, and open receivables to generate 30/60/90-day cash flow projections automatically. |
| Multi-Client Management | Manages books for multiple clients simultaneously with client-specific rules, chart of accounts, and reporting templates. One agent, dozens of clients. |
| Platform Integrations | Native integrations with QuickBooks, Xero, and Excel. Connects to bank feeds, payment processors, and ERP systems via API. |
| Anomaly Detection & Fraud Alerts | Continuously monitors transactions for unusual patterns, duplicate entries, and potential fraud indicators. Alerts accountants before issues compound. |
Deployed into your cloud, under your access controls, and yours to keep.
See AccountsGPT in Action
Request a personalized demo showing how AccountsGPT handles reconciliation, forecasting, and multi-client management for firms like yours.
No credit card required. 30-minute walkthrough.
Should I buy off the shelf or build something custom?
For most small and mid-size firms the answer is buy, because the workflows on this page are covered by tools with published prices. Build only when the workflow is proprietary, the vertical is unserved, a needed integration does not exist, or client data cannot sit in a vendor's cloud.
Intuit lists QuickBooks Online at $38, $85, $140 and $340 a month; Xero's US plans are $27, $59 and $97 after this year's rise. BILL lists $49 to $89 per user a month, plus a $49 accountant partner plan; Ramp has a free tier and Plus at $15 per user plus a platform fee. Dext prices practice plans per client, with a 10-client minimum. Specialists quote on request. Our shortlist of AI apps for finance professionals compares them (prices checked 20 to 27 October 2026).
Gaper builds and deploys production AI agents that run in the client's own cloud and that the client owns, which matters for the fourth case in particular. It is not the right answer for a firm whose real problem is that it has never turned on the automation already included in its ledger subscription. Exhaust the off-the-shelf stack first. Gaper is the AI-native implementation partner that deploys supervised AI agents you own.
The Future Accounting Firm Tech Stack
The 2026 stack is three layers, not a sprawl: a base financial platform, an AI layer and a custom layer.
The base layer (QuickBooks, Xero, or your existing platform) handles fundamental bookkeeping and serves as the system of record. The AI layer (AccountsGPT) sits on top and automates reconciliation, forecasting, anomaly detection, and reporting. The custom layer (built by Gaper engineers) addresses everything unique to your firm: proprietary client portals, industry-specific compliance tools, custom dashboards, and workflow automations that no off-the-shelf product provides.
This three-layer architecture replaces the patchwork, reduces total SaaS spend, and removes the integration maintenance. The part that matters commercially is ownership. The custom layer is built to run in your cloud and remains your property, so you are not renting your own workflow back from a vendor every year.
What does this cost, how long does it take, and what goes wrong in year one?
Subscriptions are the smallest cost: $27 to $340 a month for the ledger before per-user and per-client charges. The larger cost is staff time for data cleanup, parallel running and training, and it lands before any benefit. Year-one failures are dirty data, per-client chart variation, staff reverting to spreadsheets and vendors closing.
Old and new processes usually run in parallel for a close, staffed twice, and the MAP Survey found most firms had not yet started formal AI programs, with 35% holding no specific AI budget. Vendor exits are real. Botkeeper announced an orderly wind-down in February 2026 after 11 years. Bench shut down abruptly on 27 December 2024 and was acquired by Employer.com days later; it now trades under new ownership. Get the export format, exit terms and escrow arrangement in writing before signing.
How much does accounting automation cost? Three parts, and vendors usually quote only the first: the licence or build fee, implementation (data cleanup, integration, configuration), and the staff hours spent reviewing agent output. A custom build you own carries a higher day-one cost than a seat-based subscription and no per-seat escalation afterwards, so model the two over three years rather than one.
What are the biggest accounting industry trends in 2026?
AI moving from pilot to production, a talent squeeze eased by new CPA licensure routes and offshoring, advisory and CAS outgrowing compliance, fixed and value pricing replacing hourly billing, and tighter client data rules under Section 7216 and the FTC Safeguards Rule. Real-time reporting and SaaS consolidation follow.
Will AI replace accountants? AI will not replace accountants, but accountants who use AI will replace those who do not. AI excels at data processing and repetitive calculation; accountants excel at judgment, client relationships and regulatory complexity.
How do I get started with AI for my accounting firm? Start with a free AI readiness assessment from Gaper.io. The assessment evaluates your current workflows, identifies the highest-impact automation opportunities, and provides a roadmap with projected ROI. From there, most firms begin with AccountsGPT for core automation and expand to custom development as they identify firm-specific needs. Book a free assessment at gaper.io/appointment to see exactly how these trends apply to your practice.
What is AccountsGPT and how does it work?
AccountsGPT is Gaper's AI agent for accounting work: it reconciles, forecasts and flags anomalies inside your own systems, with a person approving anything that posts. The AccountsGPT page explains how Gaper builds a version for your stack.
AccountsGPT is a purpose-built AI agent for accounting, developed by Gaper.io. It handles automated bank reconciliation, cash flow forecasting, multi-client management, and anomaly detection. It integrates with QuickBooks, Xero and Excel, and it is deployed into your own cloud environment where the firm owns the deployment. It is part of Gaper.io’s AI agent range, which also includes Kelly (Healthcare), James (HR) and Stefan (Marketing).
Thirty minutes, no commitment. We map one workflow, make the build or buy call, and scope the smallest thing worth shipping.
Frequently asked questions
What actually changed in CPA licensure, and does the new bachelor's-plus-two-years pathway change my 2027 hiring plan?
Which of these trends carry a hard deadline, and which can I defer?
Which of these apply to a firm under 50 people, and which are Big Four problems?
What are my confidentiality and consent obligations when client data goes into an AI tool?
Who is liable when the AI is wrong, and how does this land in peer review?
If automation removes the hours, how do I price the work without cutting my own revenue?
Should I buy off the shelf or build something custom?
What does this cost, how long does it take, and what goes wrong in year one?
What are the biggest accounting industry trends in 2026?
What is AccountsGPT and how does it work?
Agentic AI Trends to Watch in 2026: From Pilot to Production
The agentic AI trends that matter in 2026 are about getting agents to production: evals, memory, governance, and ROI inside real workflows.
Apr 28, 2026
Emerging Trends in HealthTech: What Every LLM Graduate Needs to Know
AI Skills Gap in Accounting Firms: What to Train, Hire, or Hand Off
Ready to turn AI into execution?
Book a free assessment of one workflow. We map it, make an honest build versus buy call before any code, and if an off the shelf product covers the job we will tell you so.